Guide
Mortgage CRM, POS and LOS: what each one does, and what none of them does.
A CRM keeps the relationship: leads, past clients and referral partners. A point of sale takes the borrower’s application. A loan origination system is the system of record that carries the loan to closing. A lender needs all three jobs done. How many separate products it takes is a choice, and most of the daily friction on a loan sits in the gaps between them.
By Amit Ghole, President and CTO, inflooens · November 13, 2026
Definitions
Three systems, in plain words
These are established categories. Most lenders run one product from each.
CRM
Customer relationship management
Keeps track of people and the business they might bring: leads, past clients, and referral partners such as real estate agents. It reminds loan officers to follow up and runs marketing to keep relationships warm. It is busiest before an application and after a closing.POS
Point of sale
The borrower-facing front end. It takes the online application and the documents a borrower uploads, shows the borrower where things stand, and hands what it collects to the LOS.LOS
Loan origination system
The system of record for the loan. It holds the official loan file and carries it through disclosures, underwriting, closing and delivery to investors. Encompass by ICE Mortgage Technology is one example.
Side by side
How the three differ
They are not alternatives. Each does a different job at a different point in the loan’s life.
| CRM | Point of sale | LOS | |
|---|---|---|---|
| Main job | CRMWin and keep the relationship. | Point of saleTake the application. | LOSProduce a compliant, closable loan. |
| Who works in it | CRMLoan officers, marketing and sales managers. | Point of saleBorrowers, and the loan officers helping them apply. | LOSProcessors, underwriters, closers, compliance and secondary teams. |
| What it holds | CRMContacts, leads, referral partners, follow-up tasks and campaign history. | Point of saleThe application and the documents a borrower provides. | LOSThe official loan file, with disclosures, conditions and the closing package. |
| When it matters most | CRMBefore the application, and after closing. | Point of saleFrom the first application until the file is handed over. | LOSFrom application through closing, funding and delivery. |
| System of record? | CRMNo. | Point of saleNo. | LOSYes. It is the compliance system of record. |
| What it is not built for | CRMTaking an application or carrying a loan through underwriting. | Point of saleManaging leads and partners, or holding the official file. | LOSTalking to borrowers, managing referral partners or marketing. |
Where they meet
Three systems mean three handoffs
Each product can be good at its own job and the loan can still stall, because the work crosses from one to the next.
Handoff 1
Lead to application
The CRM knows the borrower as a lead. The POS meets them as an applicant. Unless the two are connected, the borrower is typed in again, and the history of who referred them and what was said can stay behind.Handoff 2
Application to loan file
The POS passes the application to the LOS. This link is usually the best built of the three, because nothing closes without it.Handoff 3
Status back to the relationship
The loan officer, the borrower and the agent all want to know where the loan stands. That lives in the LOS. Getting it back to the CRM, the borrower and the partner is where lenders add more tools, or answer the phone.
What none of them covers
The work that falls between
Lenders fill these with more tools: a texting app, a partner portal, a marketing tool, a shared inbox and a set of spreadsheets. Each one keeps its own copy of the borrower.
The conversations
Calls, texts and emails with the borrower and the agent usually happen on phones and in inboxes. None of the three systems holds them by default.One history of the loan
Each system keeps its own part. Nobody can read, in one place and in order, everything that happened on a loan and who did it.The referral partner’s view
A CRM may record that an agent sent the business. It rarely gives that agent a way to follow the loan, so they call to ask.Context for AI
An AI tool attached to one of the three sees only that system’s part of the loan. It cannot reason about what it cannot read.
Choosing
Which problem do you have?
The right purchase depends on where the work breaks down.
If leads go cold
The problem is follow-up and visibility before the application. That is the CRM’s job. Check first whether leads are being lost between systems, which no CRM alone will fix.If borrowers abandon the application
The problem is the front door. That is the POS’s job. Look at how the application reaches the loan officer and the LOS, not only at the form.If disclosures, underwriting or closing break
That is the LOS itself. Neither a CRM nor a POS replaces it, and neither does inflooens.If nobody can say where a loan stands
The problem is the gaps between the three, and another point product adds one more gap. This is the case for putting the work on one record.
Questions to ask any vendor
Before you add a fourth system
They apply to a CRM, a point of sale, or anything that claims to replace them. Including us.
- 1Which of the three jobs does your product do, and which does it leave to another system?
- 2Where does the borrower’s record live, and how many other copies of it will we be keeping?
- 3Which way does data move between you and our LOS, how often, and what happens when the LOS refuses a change?
- 4Do calls, texts and emails end up on the loan, or in a separate tool?
- 5Can a referral partner see the status of the loan they sent, and how?
- 6If we add your product, which of our current tools can we retire, and when?
Where a Mortgage OS fits
One record on top of the LOS
A Mortgage OS takes the other route: keep the LOS as the system of record, and put the relationship, the application and the conversations on one loan record on top of it. That removes the first and third handoffs and leaves one, between the record and the LOS.
inflooens is a Mortgage OS. It is not a CRM, a point of sale or an LOS. The application a borrower completes in the Borrower Portal is the loan record the team works, calls and texts are filed on it as they happen, and it syncs with the LOS in near real time, in both directions.
A lead becomes a loan in the LOS only at a real business event, such as a credit pull, a pre-approval letter or a completed application.
See the platform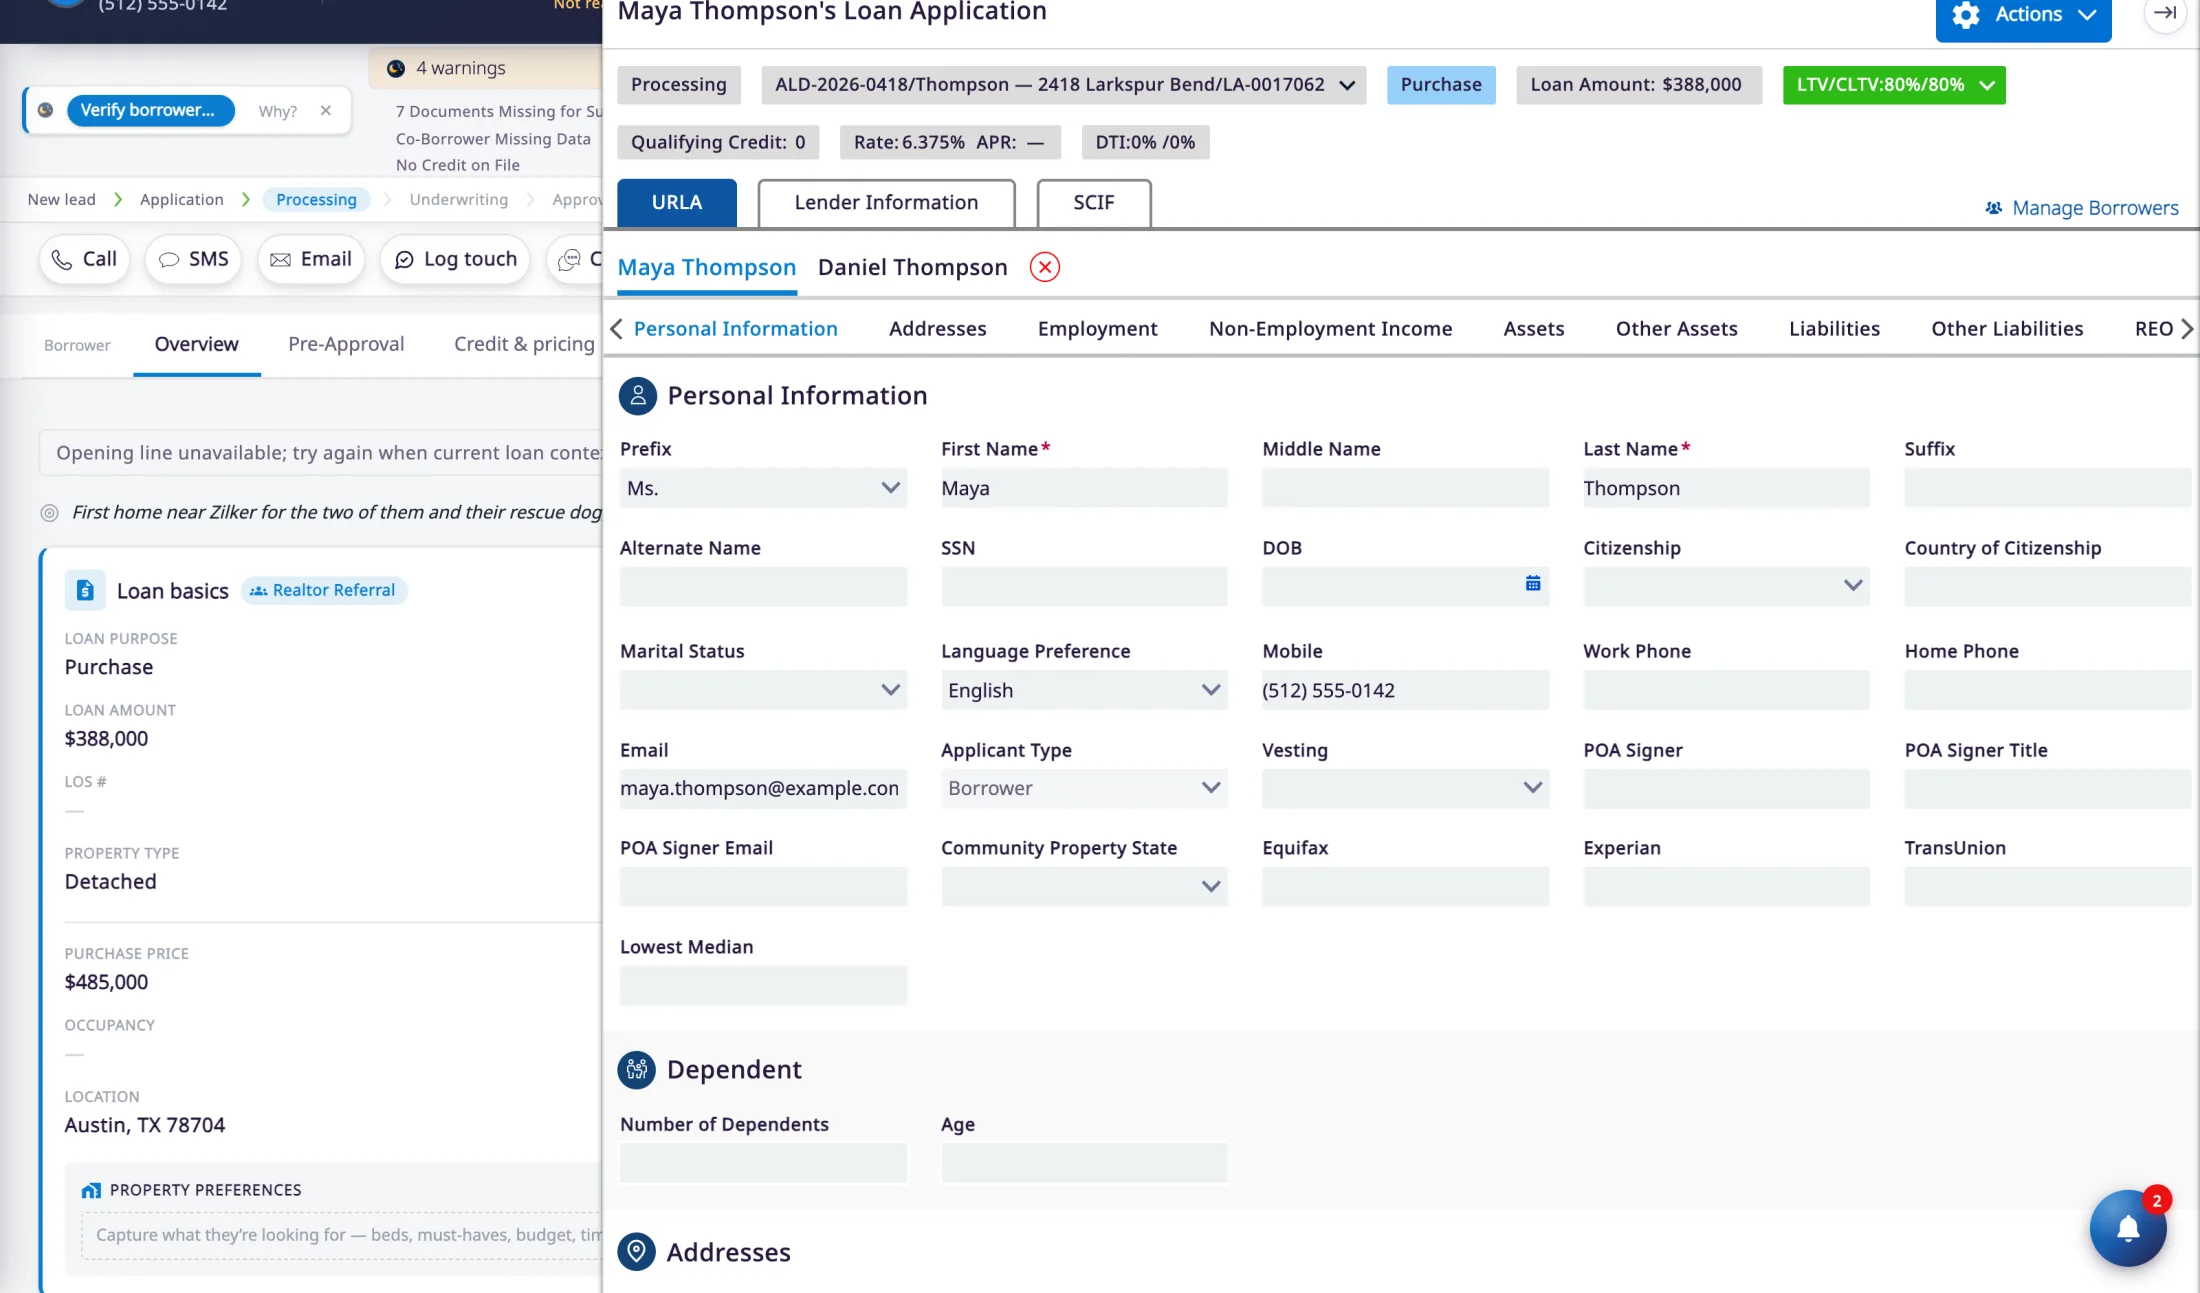
Straight answers
CRM, POS and LOS questions
- What is the difference between a mortgage CRM, a POS and an LOS?
- A CRM manages relationships: leads, past clients and referral partners. A point of sale (POS) is the borrower-facing front end that takes the application and documents. A loan origination system (LOS) is the system of record that carries the loan through disclosures, underwriting, closing and delivery. Most lenders run all three.
- What is a mortgage CRM?
- A mortgage CRM is customer relationship management software for lenders. It tracks leads, past clients and referral partners, prompts loan officers to follow up, and runs marketing. It is not where an application is taken and it is not a system of record.
- What is the difference between a POS and an LOS in mortgage?
- A point of sale (POS) is where a borrower applies and uploads documents. A loan origination system (LOS) holds the official loan file through disclosures, underwriting, closing and delivery. The POS collects. The LOS records.
- Can a CRM or a POS replace an LOS?
- No. Neither holds the official loan file, and neither is a compliance system of record. Lenders run them in front of an LOS, not in place of one.
- Does a lender need all three?
- A lender needs the job each one does: keeping relationships, taking applications and producing a compliant loan. Whether that takes three separate products is a choice. The LOS is the one that cannot be folded into the others.
- What is a Mortgage OS?
- A Mortgage OS is the operating layer where a loan is worked. It puts every person, conversation, document and tool on one loan record, on top of the loan origination system a lender already runs. inflooens is a Mortgage OS.
- Is inflooens a CRM, a POS or an LOS?
- None of the three. inflooens is a Mortgage OS: one workspace on top of the LOS. It does the work a lender uses a CRM and a point of sale for, on one loan record, and it leaves the LOS as the compliance system of record. Encompass is live today, with near-real-time, two-way, field-level sync, and integrations with other leading LOS platforms are planned.
More guides
Keep reading
- How many tools a loan officer uses, and what they cost
- Mortgage pull-through and lead conversion benchmarks
- Two-way sync with your LOS: what it should mean
- Loan officers on personal phones: what it costs
- How to track referral partners and who sent each loan
- Twelve questions to ask a mortgage AI vendor
- What an AI agent should be allowed to do on a loan
- Who should hold a lender’s loan data?
- How to pilot new software while under contract elsewhere
Keep the LOS. See what sits on top.
Thirty minutes. Your scenario. A live file.